Choosing construction accounting software comes down to one structural decision before any feature comparison: whether to run the business on a single platform where accounting, job costing, payroll, and service share one database, or to assemble a stack of point solutions connected by integrations. Everything else in the evaluation follows from that choice.
Both approaches can work. Consequently, the useful question is not which philosophy is better in the abstract, but which one fits how your labour, costs, and billing actually move through the business. This framework walks the evaluation the way a CFO should run it, criterion by criterion.
How should a CFO choose construction accounting software?
Start from the flow of money and labour, not from feature lists. Map where costs originate (field time, purchase orders, subcontracts, service calls), where they must land (jobs, work orders, the general ledger, payroll), and how many system boundaries each one crosses. Every boundary is a place where data is re-entered, synced, or lost.
That mapping produces the real requirement set. A single-division contractor whose costs follow one path may cross very few boundaries, and a stack of well-chosen tools can serve them well. In contrast, a contractor whose technicians move between projects and service calls, whose payroll must feed certified reporting and job costs simultaneously, and whose owner wants one profitability picture is crossing boundaries constantly. For that business, the count of seams in the stack is the count of places the numbers can go wrong.
The four capabilities below (job costing, integrated payroll, field service data flow, and profitability analysis) are where the single platform approach and the stack genuinely diverge. Each section explains the capability and ends with the question to ask any candidate.
1. Job Costing
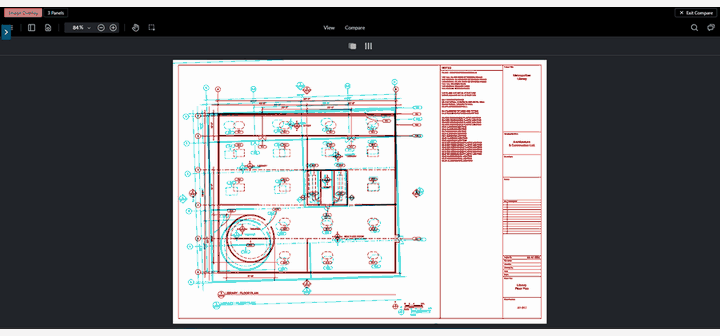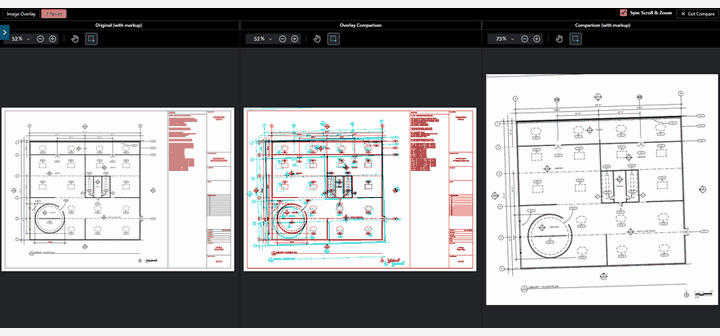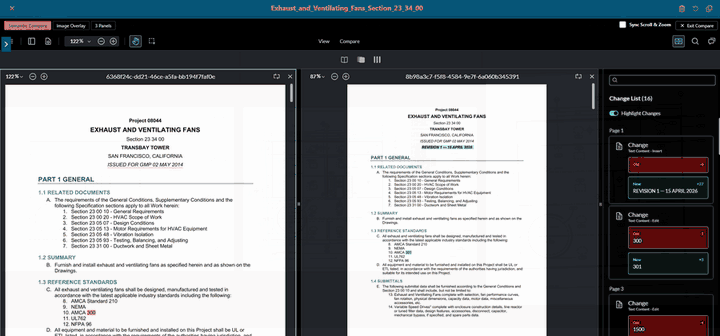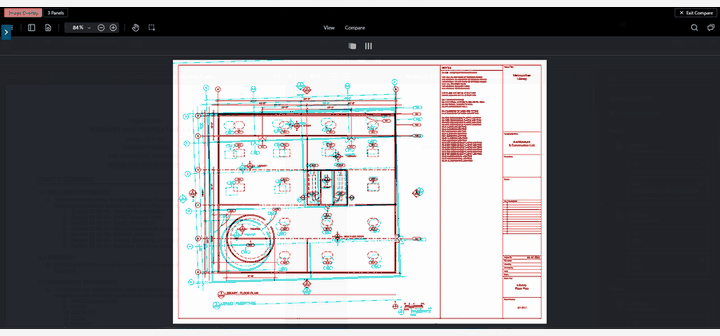
The evaluation question that separates platforms is timing. In a stack, labour often reaches job costs only after payroll runs in a separate system, and committed costs may not reach the job cost report at all, which means the project manager and the controller are managing from figures that are days or weeks old. In a single platform, the job costing ledger is the same database payroll and purchasing write to, so cost-to-date and cost-to-complete reflect today.
Question to ask: “If a labour hour travels from the field to a job cost report, how many systems does it pass through?”
2. Integrated Payroll
Construction payroll is not generic payroll, and that is where the architectures split. Multi-rate, multi-jurisdiction work, union reporting, and certified payroll on public projects all draw on job-level labour detail. When payroll runs in a standalone system, that detail either gets rebuilt by hand or arrives through an integration that must be checked every cycle. When payroll runs on the same labour records as job costing, compliance outputs are produced from data that already exists, and the payroll clerk stops being the human integration between two systems.
Question to ask: “If one approved timesheet becomes a paycheque, a burdened job cost, and a certified payroll line, how many systems does it touch along the way?”
3. Field Service Data
In a single platform, a technician’s work order is a native financial object: its hours, parts, and billing post to the ledger and to agreement costing directly. In a stack, the same data must cross into accounting through a sync, an export, or someone’s keyboard. This is the criterion where contractors running both construction and service should look hardest, because the field service platforms that dominate point-solution stacks are excellent at dispatch and weak at accounting, by design. The result is service revenue and cost that live in one system while the P&L lives in another, and a service division whose true margin is a quarterly research project.
Question to ask: “If a technician just closed a work order, where are its costs five minutes from now?”
4. Profitability Analysis
Margins assembled from multiple systems are margins built on different assumptions, which makes comparing them an exercise in false precision. This is where the stack quietly fails even when every individual tool works: the field service platform reports service margins its way, the accounting system reports project margins another way, and the spreadsheet that combines them inherits both sets of assumptions plus its own. Whether the goal is pricing service agreements, spotting profit fade, or deciding which division deserves the next hire, the analysis is only as good as the consistency underneath it.
Question to ask: “If you show me a divisional P&L comparing service and project margins on one screen, which system did each number come from, and how often does it sync?”
When does a stack of point solutions fit?
In specific, identifiable situations. A single-division contractor whose workflow lives comfortably in one lane crosses few system boundaries and may get more capability per dollar from a best-in-class specialist tool. A shop with a field tool the crews genuinely love, a disciplined integration, and someone who owns that integration as a real responsibility can make a stack work. And a very small contractor may not yet generate enough transaction volume for the seams to matter much.
The seams themselves are also getting cheaper to maintain. AI tools are increasingly used to pass data across system boundaries: reading invoices, mapping fields between platforms, and moving records that previously needed re-keying. For a stack, that is genuine relief, and it lowers the cost of each boundary. It shifts the team’s monitoring workload from tending to just verification.
The stack stops winning when boundaries multiply: when technicians cross divisions, when payroll feeds compliance and job costs at once, when the owner asks for one profitability picture and gets three versions. Take a count of the seams in your specific business, priced at what each seam costs in re-entry, reconciliation, and decisions made on stale numbers. This will inform whether the costs for these seams justifies considering a single platform solution.
When does a single platform like Jonas fit?
Jonas is a unified construction and service ERP: accounting, job costing, payroll, service management, and dispatch on one database and one general ledger. Jobs and work orders are both native cost objects, so project and service activity post to the same books; payroll runs on the same labour records that feed job costs and certified reporting; and divisional profitability is a report rather than a reconciliation.
In evaluation terms, that means the four criteria above are answered structurally rather than by integration: a labour hour passes through one system on its way from the field to the job cost report, a closed work order’s costs are on the ledger when it closes, and service and project margins are built on the same rates and the same overhead basis. For contractors whose money and labour cross divisions constantly, that is the architecture the framework points toward.
Because the service division and the construction division share one ledger, one payroll, and one set of burdened labour rates, the service margin is built on the same basis as project margins and the two are directly comparable. A contractor can pull what any agreement has earned to date, compare service and install margins on one screen, and price renewals on accumulated actuals rather than memory.
"I used to use multiple software, one to run the equipment side, one to run the accounting side. To run a quick report to see where you were wasn't just a headache, it was futile."
Jason Petty, Director of Finance, Metal Building Group
Run the evaluation against your own numbers. Book a demo with a Jonas specialist.
Common Questions
What does a stack of point solutions actually cost beyond the subscriptions?
The full cost is subscriptions plus the integration itself (setup, middleware, and maintenance), plus the labour that tends the seams: re-entry, sync checking, and month-end reconciliation between systems. The largest hidden cost is usually decision quality, since numbers assembled across systems arrive later and less consistently than numbers produced in one.
Who owns the stack integration when it breaks?
That question deserves an answer in writing before any stack software is purchased. When a sync fails between a field tool and accounting, each vendor can plausibly point at the other, and the contractor’s own staff becomes the integrator of last resort. If no one inside the business is named as the owner of each integration, the realistic answer is the controller, on month-end week.
How do you distinguish real integration from a checkbox in a demo?
Ask to watch a transaction travel. A labour hour from field entry to a burdened job cost, or a closed work order to the general ledger. Real integration shows the record arriving with full detail, immediately, without an export step.
Can we keep a point solution the team loves and integrate it?
Sometimes, and the framework tells you when. If the tool sits at a low-boundary edge of the business, few costs crossing in or out, a disciplined integration with a named owner can preserve it. If it sits on a high-traffic boundary, such as field labour or service billing, every transaction pays the seam penalty, and the affection for the tool should be weighed against what the seam costs monthly.
Does moving from a stack to a sinlge platform mean losing best-in-class features?
It can mean trading some peak capabilities in single functions for consistency across all of them, and the right answer depends on where your risk lives. A contractor rarely loses money because one department lacked a premium feature. Contractors lose money on labour landing in the wrong bucket, margins nobody trusts, and compliance rebuilt by hand. Make a short list of the non-negotiable features you need to have when reviewing vendors.